Complete MSME files. Ready for your credit officer to decide.
Finclus matches each small business to the government schemes it qualifies for, builds the file, and has it checked by retired bankers and chartered accountants. Your officer reads it and decides.
- Scheme-matched
- Verified before it reaches you
- RBI Digital Lending aligned
Finclus is a Lending Service Provider (LSP) and technology service provider. It never lends.
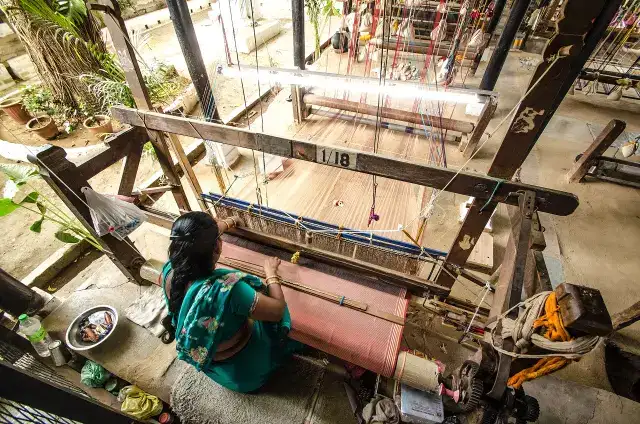 Artisans
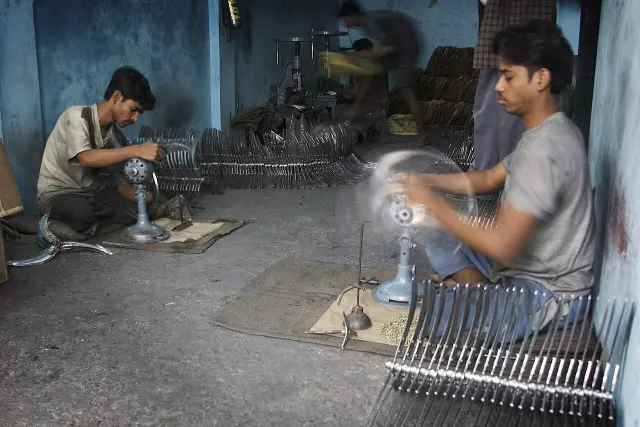 MSMEs
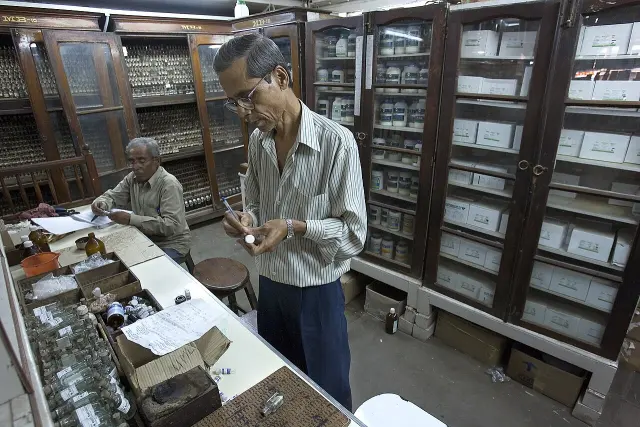 Professionals
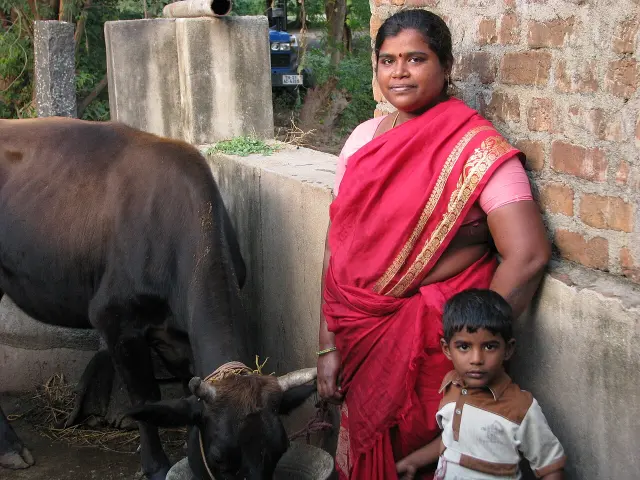 Dairy and livestock
 Entrepreneurs
 Women’s groups
The short version
What a missed sub-target costs
A micro-enterprise shortfall goes into RIDF and similar funds at returns the RBI fixes.
What reaches your officer’s desk
We arrange the loan file, the subsidy claim and the state permissions together, so the file that reaches your officer is complete.
Start with one product line
Pilot one product line, in your VPC, on your rules.
What a missed sub-target costs
Commercial banks carry a micro-enterprise sub-target of 7.5% of adjusted net bank credit. A shortfall against a target or sub-target goes into RIDF and similar funds with NABARD, SIDBI and others, at returns the RBI fixes, not at what the same money would earn as loans.
Source: RBI Master Directions, Priority Sector LendingEvery complete file your officer can sanction is micro-enterprise credit on your book instead of a deposit at a rate you did not choose.
What every file is built from
of adjusted net bank credit is the RBI micro-enterprise sub-target.
Source: RBI Master Directions, Priority Sector LendingIllustration with sample data, not a real borrower.
What reaches your officer’s desk
We arrange the loan file, the subsidy claim and the state permissions together, so the file that reaches your officer is complete.
- Borrower
A scheme-backed small business, with consent.
- Finclus prepares
Agentic screen
Identity, collateral, DSCR, fraud and compliance checked.
- Finclus prepares
Document prep
Project report and subsidy papers by chartered accountants.
- Lender decides
Credit officer
Your officer reviews the file and signs it off.
- Lender decides
Decision
Sanction or rejection, yours to make.
Steps two to five can run inside your VPC: borrower data never leaves it.
Loans
Files shaped the way your credit committee reads them, by retired bankers.
Subsidies
The scheme’s subsidy claimed alongside the loan, subject to the scheme’s own terms.
Permissions
Udyam, FSSAI, factory licence, pollution consent, fire NOC: filed through the state single window before disbursal.
A file as it usually arrives, and a Finclus file
| Part of the file | Usually | From Finclus |
|---|---|---|
| Scheme fit | Unchecked until your officer reads it | Matched to the scheme, every figure cited to its source |
| Credit guarantee | Eligibility worked out after the file arrives | Checked against CGTMSE conditions where the borrower qualifies, ready for you to apply |
| Project report | Thin, or arrives later | Built by chartered accountants on a credit model your officer recognises |
| Subsidy | Claimed after sanction, if at all | Prepared with the file and followed up until it is credited |
| Permissions | Pending, holding up disbursal | Filed through the state’s single window portal and tracked |
| Documents | Collected in rounds | Checked against the scheme’s list before the file reaches you |
| Who checked it | No one before your officer | Retired bankers, retired IAS officers, chartered accountants and lawyers |
Why good borrowers get turned down, and what we fix
No project report, or one the branch cannot use
Chartered accountants build it on the bank's own credit model
Scheme never checked against its own conditions
Eligibility read line by line from the official guidelines
Papers arrive in rounds, weeks apart
Every document the scheme lists, collected before the file moves
Udyam, FSSAI or a pollution NOC still pending
Filed through the state single window and tracked to issue
Risk is filtered before the file reaches your desk
Identity, collateral, DSCR, fraud and compliance, checked up front. Unsure files go to a human.
Schematic. Widths show the order of the checks, not measured shares of files.
Where the savings come from
Finclus targets the two costs you can compress: operating and credit.
- Cost of funds
- Operating cost
- Credit cost
- Net margin
Schematic, not measured figures. Fewer file touches lower operating cost; screened, scheme-backed files aim at lower credit cost. A pilot is how you measure both on your own book.
The borrowers we bring you
Small manufacturers, dairy and livestock units, shops, professionals and women’s groups, each matched to the schemes you already lend under.
 Farmers
 Small workshops
 Artisans
 Street vendors
 Dairy and livestock
 Women’s groups
Illustrative photos. The people shown are not Finclus customers.
Built for the RBI Digital Lending Directions
Finclus is a Lending Service Provider (LSP). It never lends; your institution does.
Your institution is named
The borrower is told up front which regulated lender the loan is with.
Your Key Fact Statement
The borrower gets your KFS, with the all-in annual cost, before signing.
Our fees are paid by you
Finclus is paid by the lender. The borrower is never charged for loans. Any desk fee for subsidy or project-report (DPR) work is quoted to the borrower up front.
Technology
LOS + LMS as a service, on your rails. No core replacement.
Trust
In your VPC. Consent-gated, DPDP-compliant, full audit trail.
Human-owned decision
Every decision is human-owned: Finclus screens and prepares, your officer decides.
Source: RBI Master Directions, Digital Lending · RBI Master Directions, Priority Sector Lending (micro-enterprise sub-target 7.5%)
People who have sat on your side of the desk
Files are checked by retired bankers, retired IAS officers, chartered accountants and lawyers.
- Retired bankersshape the file the way a credit committee reads it
- Retired IAS officersknow how schemes and state permissions are run
- Chartered accountantsbuild the project report and the cash flows
- Lawyerscheck title, security and documentation
Start with one product line
Pilot one product line, in your VPC, on your rules.
- 1
You choose the scope
One product, one region, the schemes you already lend under.
- 2
Your credit policy applies
Files are prepared to your checklist; your officers sanction or decline.
- 3
You judge the files
Continue only if the files are worth your officers’ time.
Founding lenders
We are opening Finclus to a first group of banks and NBFCs. Pilot terms are agreed per lender.
Lender-relevant scheme feed
Schemes with guarantee coverage, interest support or loan features, pulled from the Finclus corpus.
Loading corpus data…
Sample engine outputs: sanction factors, demand estimate, pre-screen
Sanction-factor assessment
Honest read on the factors affecting sanction, never a fixed percentage.
Loading corpus data…
Backtest demand estimate
Illustrative pipeline estimate based on corpus scheme coverage.
Loading corpus data…
Pre-screen specification
Preliminary eligibility screening against corpus criteria.
Loading corpus data…
Send us one product line. We will send you files.
A short call with your credit or MSME head is enough to scope a pilot. If the files do not save your officers time, you stop.